
Updated 10/20/2026
What Houston Homeowners Should Do First
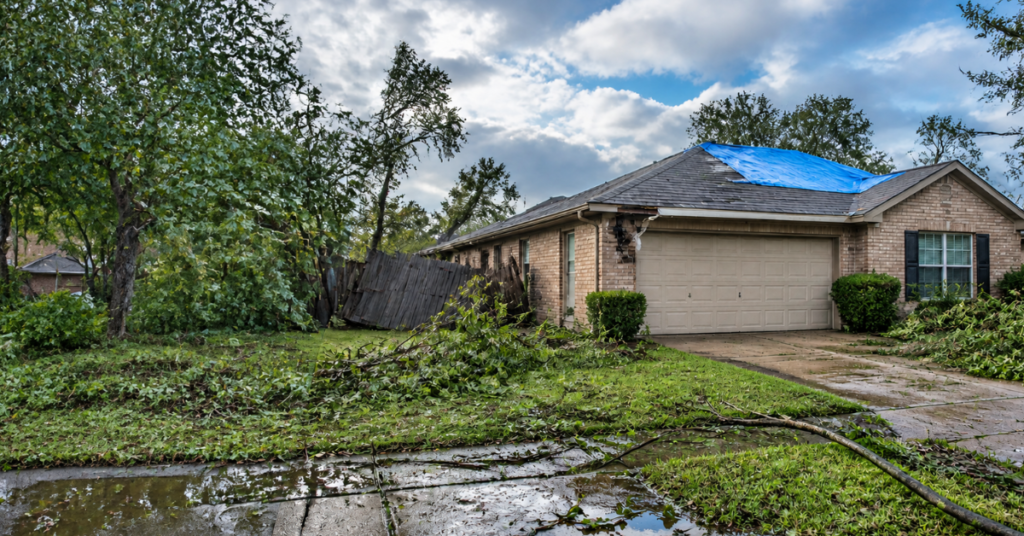
After a hurricane or major storm damages your home, stay safe first, then document every bit of damage with photos and video, make temporary repairs to stop more damage, report your claim to your insurance company quickly, and hire a local, licensed and insured contractor for permanent repairs. Avoid anyone who knocks on your door offering to waive your deductible or handle your insurance claim. Both are illegal in Texas.
On July 8, 2024, Hurricane Beryl made landfall near Matagorda as a Category 1 hurricane and moved across the Houston area, knocking out power to more than 2 million CenterPoint customers (Community Impact). Master Remodelers, a family-owned remodeling company that has served Houston, Pearland, Friendswood, League City, Clear Lake and Galveston since 1998, helped neighbors repair roofs, siding, windows and patio covers after that storm. Here’s what we’ve learned about recovering after a storm.
Table of Contents
Step 1: Stay Safe
- Stay away from downed power lines and standing water near them. Report them to your electric utility.
- Run generators outdoors only, far from doors and windows, to avoid carbon monoxide poisoning.
- Don’t climb on a damaged roof. Take photos from the ground.
- If you smell gas, leave the house and call your gas company from outside.
Step 2: Document the Damage
Before you clean up or throw anything away:
- Take photos and video of every room and every side of the house, including the roof, siding, windows, fences and patio covers.
- Photograph damaged belongings, and write down what they are and roughly when you bought them.
- Keep receipts for tarps, plywood, hotel stays and other storm-related costs.
Step 3: Prevent More Damage
Most insurance policies expect you to take reasonable steps to protect your home from further damage. That can mean:
- Tarping roof leaks
- Boarding up broken windows
- Drying out wet areas quickly to limit mold
Keep the damaged materials or photos of them, so your adjuster can see them.
Step 4: Report Your Claim Quickly
Call your insurance company or agent as soon as you can. Wind damage and flood damage are often covered by different policies:
- Homeowners insurance usually covers wind damage, unless you live in an area where wind is covered separately.
- The Texas Windstorm Insurance Association (TWIA) covers wind and hail for many homes along the Texas coast, including parts of Galveston and Brazoria counties. TWIA claims must be reported within one year of the date the damage occurred.
- Flood damage is covered only by a separate flood insurance policy.
Texas law also gives insurance companies deadlines to acknowledge, decide and pay claims. The Texas Department of Insurance explains them in its guide to getting your insurance claim paid. If you have questions or a complaint, call the TDI Help Line at 800-252-3439.
Step 5: Watch Out for Storm Chasers
After every big storm, out-of-town contractors flood Houston neighborhoods. Some do good work, but many disappear after taking a deposit. Red flags:
- Door-to-door sales right after the storm, especially with pressure to sign today
- Offers to waive or “cover” your deductible. That’s illegal in Texas, and you must pay your deductible.
- Promises to handle or negotiate your insurance claim. Texas doesn’t allow a contractor to act as your public adjuster.
- Large cash payments up front
- No local address, no reviews and no proof of insurance
Before you hire anyone: check their BBB rating and Google reviews, ask for proof of insurance, get a written contract and written estimate, and make sure they’ll pull any required permits.
Step 6: Get a Written Estimate and Make Permanent Repairs
A reputable contractor will inspect the damage, explain what needs to be repaired or replaced, and give you a detailed written estimate you can share with your insurance company. Master Remodelers provides:
- A thorough inspection of your roof, siding, windows and interior
- Photos and a detailed written estimate of the repairs
- Permits, inspections and the full repair, from start to finish
What we don’t do: we don’t act as your adjuster or negotiate your claim, and we won’t waive your deductible. If you want someone to represent you with your insurance company, Texas allows you to hire a licensed public adjuster. Learn more in our post on public adjusters.
Storm Damage We Repair
- Roofs: missing shingles, leaks, damaged decking, flashing and gutters. Start with a free roof inspection.
- Siding: torn, cracked or missing siding, soffit and fascia
- Windows: broken glass and damaged frames, including upgrades to impact windows
- Patio covers and porches
- Interior water damage: drywall, flooring, cabinets and trim
See all of our storm and disaster repair services.
Rebuild Stronger for the Next Storm
Repairs are a chance to make your home tougher:
- Impact windows with laminated glass that stays in the frame if it breaks
- Stronger roofing, with better underlayment, fastening and wind-rated shingles
- Reinforced garage doors, one of the weakest points in high wind
- Secured patio covers and outdoor structures
Ask your insurance agent whether any of these upgrades could lower your premium.
Paying for Storm Repairs
Insurance doesn’t always cover everything, and your deductible can be large. Master Remodelers offers home improvement financing through Slice by FNBO, subject to credit approval, so you can start repairs without waiting.
Why Houston Homeowners Choose Master Remodelers
- Family owned and operated since 1998, led by President Donald “Don” Borden.
- Rated A+ by the BBB, and winner of the Pulse of the City Award in 2025 and 2026.
- Licensed and insured.
- Local: we live and work in the Houston area, so we’re here long after the storm.
- Free, detailed written estimates.
Frequently Asked Questions
Make sure everyone is safe, then photograph and video all of the damage before cleaning up. Make temporary repairs, like tarping the roof or boarding windows, to prevent more damage, keep your receipts, and report the claim to your insurance company as soon as possible.
If you’re insured by the Texas Windstorm Insurance Association (TWIA), you must report a claim within one year of the date the damage occurred. Other insurance policies set their own deadlines, so check your policy and report damage as soon as you can.
No. It’s illegal in Texas for a contractor to offer to waive, rebate or absorb your deductible, and you are required to pay it. Your insurance company can ask for proof that you paid.
No. Texas doesn’t allow a roofer or contractor to act as a public adjuster on a project they’re working on. A contractor can inspect the damage and give you a written estimate to share with your insurer. If you want someone to represent you, you can hire a licensed public adjuster.
Be cautious of door-to-door sales right after a storm, pressure to sign immediately, offers to waive your deductible, promises to handle your claim and requests for large cash payments up front. Hire a local contractor with a physical address, good BBB and Google reviews, proof of insurance and a written contract.
Yes. Master Remodelers offers home improvement financing through Slice by FNBO, subject to credit approval. Financing is provided by First National Bank of Omaha (FNBO) through Slice, not by Master Remodelers.
Need Storm Damage Repairs?
Related: Patio Covers · Outdoor Kitchens · Windows · Kitchen Remodeling · Garage Conversions · Roofing and Siding